Meta Trend Online ShopPLAN BEAUTIFULLY, LIVE BRILLIANTLY
🛒 Cart
Sign In
Sign Up
One budget planner does not fit every payday. We split ours into four — Monthly, Weekly, Biweekly and Paycheck — because a salary paid monthly and wages paid every two weeks are two different money lives. Here is how each one works, who it fits, and what it costs.
Most budgets do not fail because people are careless with money. They fail because the budget runs on the wrong rhythm. A monthly planner is useless to someone paid every two weeks — by the second payday the page is already a mess — and a weekly planner feels like homework to someone whose salary lands once a month. The tool has to match the way the money actually arrives, or it gets abandoned by February.
That is exactly why our shop does not sell one budget planner. It sells four, split by payday rhythm: Monthly, Weekly, Biweekly and Paycheck. Each one is a separate Excel + PDF file, each costs $3 (Rs 830), and all four come together in the Budget Planner Bundle for $7 (Rs 1,940). This post explains what each one is for, who it fits, and how to pick yours in two minutes — including the honest limits at the end.
When we first listed a budget planner, it was a single monthly file, and buyers kept asking the same question in different words: "Does it work for weekly pay?" "What if I get paid every two weeks?" "Can I plan each paycheck separately?" A monthly sheet can be bent to fit those rhythms, but bending a tool every payday is friction — and friction is what kills a habit.
So instead of one file with compromises, we built four files, each designed around one rhythm. The structure inside each is the same idea — plan the money coming in, list what must go out, track what actually went out, review the gap — but the time blocks are different, because the time blocks are the whole point. A weekly planner has 52 small weeks to fill, not 12 big months. A paycheck planner starts when the money lands, not on the 1st of the month.
That split also keeps the price honest. Nobody has to pay for four planners to get the one they need: each is $3 (Rs 830) on its own. The bundle exists for the household that genuinely wants all four — for example, a couple where one partner is salaried monthly and the other is paid biweekly — and at $7 (Rs 1,940) it costs less than three singles, let alone four.
Here is the short version of each file, and the buyer it fits best:
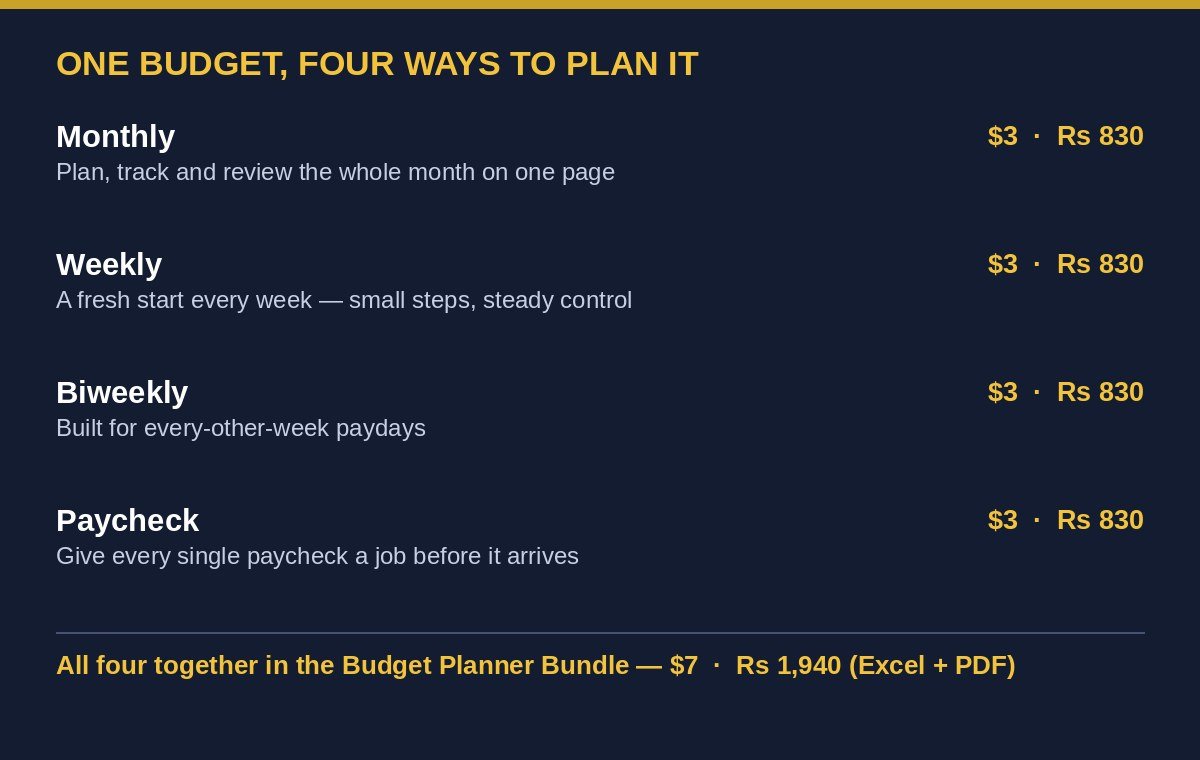
Every file is Excel + PDF, so you can use it on a computer, print it, or both. And because these are our own products, the same files are sold on our shop and on our Etsy store — the shop price is the one quoted here.
Bought separately, the four planners cost $12 (Rs 3,320). The Budget Planner Bundle is $7 (Rs 1,940) — a saving of $5, or Rs 1,380, against buying all four one by one. It makes sense in three cases: a household with two different pay rhythms, a buyer who wants to try weekly planning for a month and monthly planning after that, or a seller-style buyer who wants to see the full range before choosing a favourite.
It does not make sense if you already know your rhythm. If you are paid monthly and your bills are monthly, buy the Monthly planner for $3 and ignore the rest. A bundle you will not open is not a bargain at any price — it is clutter, and clutter is the enemy of the habit you are trying to build.
If one of these four sounds like your payday, start with that one file, fill in a single cycle honestly, and review it at the end of that cycle before judging it. A budget earns its keep in the review, not in the planning. You can find all four, and the bundle, in the Budget section of the shop — and if you ever decide to sell a planner of your own, our beginner's guide to selling digital products walks through the whole path, from file to first sale.
Selling to buyers abroad is the easy part — getting the money into your hands in Pakistan is where most new sellers get stuck. Here is how Payoneer works, what it costs, and how it fits our own monthly payout.
You do not need a new skill to start selling — you need one useful file. Twelve digital product ideas that work for Pakistani sellers, from planners and spreadsheets to study packs and clipart.
You already have the skill, the examples and the clients' questions — now package them once and sell the file again and again. Five freelance services that become real digital products.